


Fixed rate home loans with offset facilities
Many lenders offer offset facilities with a fixed rate home loan, Qantas Money Home Loans offer multiple offset facilities per loan on some of our loans++. Read on to find out more.

Want the certainty of knowing what your repayments will be but also enjoy the flexibility to save on interest payments? With an offset facility, you can have both.
Fixed rate home loans
A fixed rate home loan offers you the security of locking in your home loan rate, giving you the certainty of fixed repayments, so you know exactly how much you will need to allocate to your home loan over a set period and can budget accordingly. This means your rate won’t increase if market conditions result in your lender increasing their rates, something that can happen with a variable rate home loan. However, if market conditions result in your lender decreasing their rates, you may not benefit from that decrease.
One downside to fixed rates is they can limit your additional repayment amount, which means you won’t be able to pay off your loan faster by making extra repayments. For example, if your situation changes (like you get a pay rise or come into a little extra money), you won’t get the benefit of being able to pay down more of your principal loan amount to reduce the amount of interest you pay over the life of your loan.
Another downside to a fixed rate loan, is that break cost fees may apply if you break the terms of your fixed rate home loan.
How offset facilities work
An offset facility works similarly to a transaction account. However, because it is linked to your home loan, the balance of money in your offset facility is used to reduce (or offset) the amount of interest you pay on your home loan. Also, you will usually have full access to your money via an online portal and/or app, and a debit card. Learn more about the types of offset facilities here.
You can choose to have your salary deposited into your offset facility and set up direct debits - just as you would a transaction account. What makes it different from other transaction accounts, is how it’s linked to your home loan. At the end of each day, the balance of any offset facilities is taken away from the balance of your home loan. The amount you pay interest on is then calculated on the difference between them:
Your loan amount <minus symbol> the savings you have in your offset facilities.
This means if you have money in your offset facility, you will pay less interest over the life of the loan and could pay back your home loan faster. It’s a way to reduce the amount that your home loan interest is calculated on without having to make extra repayments and needing to redraw them later.
If you have a fixed rate home loan and the balance in your combined offset facilities exceeds the permitted threshold during a 12-month period, a break cost may be charged.
What is the benefit of having multiple offset facilities?
Some lenders only provide one offset facility. However, there are some lenders, like Qantas Money Home Loans, that can provide you with multiple offset facilities*. Being able to access multiple offset accounts / sub-accounts provides you with a cash flow management tool. Different facilities can be used for various saving purposes - one for bills, one for holidays, one for home renovations, and so on. So you can easily see and keep track of your savings goals.
What’s more, you’ll usually also be able to receive a debit card for each offset facility, ensuring you have access to your funds, all the time.
Plus, the money in each one of your offset facilities is linked to your home loan, helping to reduce the interest you are paying on your property. This is because the combined balance of your offset facilities reduces the balance of your home loan for scheduled interest calculations.
How is an offset facility different from a redraw facility?
A redraw facility allows you to withdraw any additional repayments you have made into your home loan, less one repayment.
Bank offset accounts are different from redraw facilities because they are a separate account from your home loan.
Non-bank lenders provide offset sub-accounts. While an offset sub-account works similarly to a traditional bank offset account - allowing you to transact, save and spend - it is not a separate account, nor a bank deposit account. Rather, an offset sub-account is a feature linked to your home loan and is essentially a fully transactional redraw account. This means the ‘offset’ amount cannot have a balance greater than your home loan balance, and the offset sub-account is not covered by the government deposit guarantee.
Depending on the lender, there may be restrictions on the total amount you can add into your Fixed Rate Home Loan offset facility each year, and fees to pay if you exceed this limit.
Find out more about offset sub-accounts here.
Why an offset account works well with a fixed rate loan
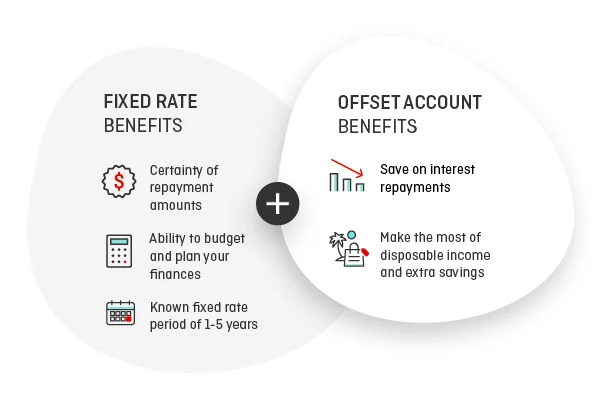
Fixed rates often have a maximum amount of additional repayments that can be made per fixed term, so you can still make extra repayments into your home loan to help reduce the interest you pay.
An offset facility reduces the balance amount that your interest is calculated on. So you can have the certainty and stability of a fixed rate, while also reducing the interest charged on your home loan.
It is worth noting, if you have a fixed rate home loan and the balance in your combined offset facilities exceeds the annual limit permitted on your loan, a fee may be charged.
Need any help?
Our home loans experts are available on 1300 992 700 Monday to Friday: 8:00am to 6:30pm and weekends 9:00am to 5:00pm (AEST) to help answer any questions you may have. You’re under no obligation to apply, we just want to help you find the Qantas Money Home Loan that’s right for you.
You have to be a Qantas Frequent Flyer member to apply for a Qantas Money Home Loan. This website contains general advice only. This information has been prepared without considering your objectives, financial situation or needs. You should consider your circumstances before acting on this information.
*++ Offset facilities: Offset facilities are only available on the Qantas Money Offset Home Loan and Qantas Money Atlas Home Loan for both fixed and variable products.
Offset facilities must be linked to an eligible Home Loan account and can only be linked to one eligible Home Loan account at any one time.
Up to 6 offset accounts are available per Qantas Money Offset Home Loan. Linked offset accounts must be in the same customer name/s as the loan account.
Up to 10 offset sub-accounts are available per Qantas Money Atlas Home Loan. Linked offset sub-account/s must be in the same customer name/s as the loan account. For Atlas Fixed Rate Home Loans, offset funds are limited to $20,000 per annum total across all sub-accounts. Additional funds may be subject to Early Repayment fees. All fees can be found on the fees page.
How to set up the offset facilities may change from time to time, and will be advised during the application process.
This is general advice only. Consider the relevant home loan Terms and Conditions and TMD, and your personal circumstances before you take out this product. Details can be found on the Terms and Forms page.
Complaints about the home loan or offset facilities should be made to the credit provider and provider of the offset facility by emailing:
Basic and Offset Home Loans funded by Bendigo Bank: myloan@homeloans.qantasmoney.com
Atlas Home Loans funded by ColCap Financial: colcap.myloan@homeloans.money.qantas.com
 Application enquiries
 Frequently asked questions