


Fixed rate home loans that come with a holiday every year
Qantas Points every year+
Basic Home Loan
Owner occupied · Principal & interest
with 50% LVR
Why come on board with a Qantas Money Home Loan?

100,000 points every year
Enjoy 100,000 Qantas Points every year for the life of your home loan for up to 6 properties+†

Competitive rates
We’ve partnered with select lenders to secure competitive rates on all our loans

Easy application process
Apply online to get an answer in minutes

Help when you need it
Our home loan experts are here to help with your application 7 days a week
Key benefits of a fixed rate home loan
Our fixed rate home loans have a fixed interest rate and set repayments that won't change during the fixed term so you can lock in a great rate that won't change, regardless of any future RBA rate rises during the fixed rate period##.

100% offset facilities available++
Our Atlas and Offset home loans provide the option to add offset facilities across all types of loans including fixed rate loans - giving you more flexibility to manage your loan, your way.

Repay faster and save on interest
Our fixed rate home loans let you pay up to $20,000 a year in additional loan repayments.

A redraw facility
Your Qantas Money Home Loan comes with a redraw facility, which means you can access any extra payments you’ve made on your loan, less one month’s minimum loan repayment, for free. Get the benefit of reducing the interest you pay - but still have access to your money if you need it.
Get a more rewarding home loan and earn 100,000 points every year
Where could 100,000 Qantas Points take you?
Who is travelling?
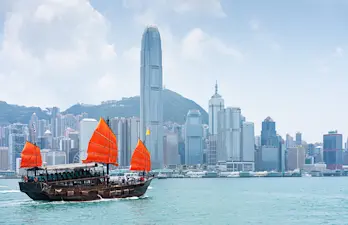
Melbourne to Hong Kong
Return flight for one
$305 in taxes and carrier charges
Conditions apply ±
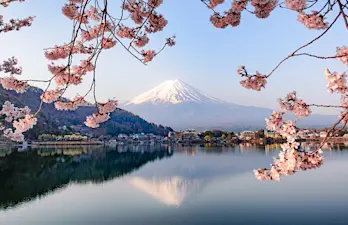
Sydney to Tokyo
Return flight for one
$305 in taxes and carrier charges
Conditions apply ±
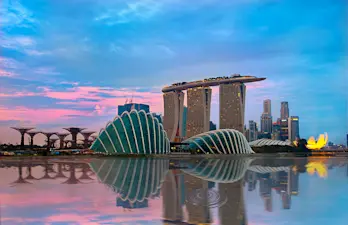
Sydney to Singapore
Return flight for one
$322 in taxes and carrier charges
Conditions apply ±
Frequently asked questions
A fixed rate home loan is one where the interest rate is locked in for a certain period (usually 1-5 years). At the end of this period you can either commit to another fixed rate or revert to a variable interest rate. The ‘re-fix’ interest rate will depend on the rates available in the market at that time...
This will depend on your personal situation and preferences. If you prefer the security of knowing exactly how much your repayments will be every month, then a fixed rate home loan locked in for a set period may be better for you.
If you don’t mind your interest rate changing according to market fluctuations and would rather have a loan with features that can help you pay it off quicker, then a variable rate loan might be a better option.
With a Qantas Money Home Loan, both our fixed rate and variable home loans come with redraw facilities and our Offset and Atlas Home Loans also come with the option to include multiple offset facilities.
Both banks and non-bank lenders can provide offset facilities. Banks provide offset accounts and non-bank lenders provide offset sub-accounts. Both offset accounts and offset sub-accounts reduce the interest you pay on your loan, however there are some key differences to be aware of:
- Structure: an offset account is a separate bank account linked to the home loan, whereas a sub-account forms part of the loan itself. Both hold funds that are accessible via debit cards, BPAY and digital wallets.
- Limits: because an offset sub-account forms part of the loan itself, the balance of funds within the account cannot exceed your home loan balance. There is no such limit on an offset account, though banks may put their own limit on the portion of funds able to be used as offset.
- Account closure: because an offset sub-account forms part of the loan itself, the sub-account will be closed when the loan is closed. If you intend to keep the offset amount as cash when you close the loan, you will need to move it to a different account prior to your lender providing your final payout figure. This is not the same for bank offset accounts - because they are a separate bank account, they can continue to exist once your loan account is closed.
- The Government’s Financial Claims Scheme (FCS) deposit guarantee: funds in an offset account are covered by the FCS guarantee, however funds in an offset sub-account are not covered by the FCS guarantee because the sub-account forms part of your loan rather than being a separate deposit account. It’s worth noting that if a non-bank lender closes down, your loan may be transferred to another party, and you would continue making repayments to that new party. T he balance in your offset sub-account is not lost and should continue to reduce, or be set off against, your loan balance.
Qantas Money has partnered with Bendigo Bank and ColCap Financial, two of Australia's experienced lenders, to offer a range of home loans with competitive rates that earn you Qantas Points.
Learn more
Need any help?
Our Home Loan experts are happy to help with your application 7 days a week.
New customers:
Monday to Friday from 8:00am to 6:30pm, or on weekends from 9:00am to 5:00pm (AEST).
Existing customers with loans funded by Bendigo Bank:
Monday to Friday from 8:30am to 8:30pm, or on weekends from 9:30am to 4:30pm (AEST).
Existing customers with loans funded by ColCap Financial:
Monday to Friday from 8:00am to 6:30pm, or on weekends from 9:00am to 5:00pm (AEST).
 Application enquiries
 Frequently asked questions
Important Information
Credit is provided by Bendigo and Adelaide Bank, ABN 11 068 049 178 AFSL/Australian Credit Licence 237879, or Columbus Capital Pty Limited ACN 119 531 252 (Australian Credit Licence 337 303), a wholly owned subsidiary of ColCap Financial Limited, depending on the product selected. Credit criteria, fees and charges apply. Based on the funder's credit criteria.
Before you take out a Qantas Money Home Loan, consider the relevant TMD and your personal circumstances.
This product is only available to Australian residents who are Qantas Frequent Flyer members. A joining fee may apply. Membership and the earning and redemption of Qantas Points are subject to the Qantas Frequent Flyer terms and conditions.
* Interest rates: All lending interest rates are for new loans only and may differ for existing loans. Rates are subject to change. Fees and charges may be applicable and can be found on the Rates and Fees page online.
^ Comparison rates: Important information about comparison rates: the comparison rates displayed are calculated for a loan of $150,000 over 25 years. If a comparison rate relates to a loan with a fixed interest rate, the comparison rate has been calculated on the basis that our current applicable variable rate will apply at the end of the fixed rate period. If a comparison rate relates to an interest only loan with a fixed rate, the comparison rate has been calculated on the basis that the interest only period is the same duration as the fixed rate period. If a comparison rate relates to an interest only loan with a variable interest rate, the comparison rate has been calculated on the basis that the interest only period is 5 years. WARNING: the comparison rate is true only for the example given and may not include all fees and charges. Different terms, fees or other loan amounts might result in different comparison rates. All interest rates are subject to change without notice. Fees and charges can be found on the Rates and Fees page.
+ 100K Bonus points offer: Qantas Frequent Flyer members will earn 100,000 Qantas Points upon settlement of their Qantas Money Home Loan. Members will earn the annual bonus of 100,000 Qantas Points three months after the settlement anniversary of their Qantas Money Home Loan for up to 30 years. Both upfront and ongoing points will be credited to the member’s Qantas Frequent Flyer account within 8 weeks of the Qantas Points being earned, provided the loan is in compliance with the Qantas Money Home Loans Points Eligibility Policy, not in arrears or default and the loan is not the subject of hardship relief or assistance. For joint applicants, the Qantas Points by default will be awarded to the primary applicant annually unless the primary applicant opts to either split the points between the secondary and primary applicants or award the points in full to the secondary applicant.
† Maximum number of loans: Limits apply. A member may only take out a loan and earn Qantas Points for up to a maximum of one owner occupied property and five investment properties (depending on individual circumstances). Please contact us if you wish to apply for loans for six properties.
Ω Calculator results: The results are a guide only. They are not a quote, credit approval or offer of credit. The results are not advice on how much you can or should borrow, which product you should choose, the product features or options, or about making extra payments. You should speak to us or obtain professional advice about a loan that meets your requirements and objectives. The offset account is not available for all loan products. There are restrictions and/or certain fees payable for additional payments for some products e.g. during the fixed term of a loan. The results assume regularly scheduled payments and that the interest rate does not change, and do not include any discount period. Interest rates are subject to change except during a fixed rate period. The rates and repayment amounts do not include lenders mortgage insurance if applicable.
## Lock in fixed rate: For the Basic and Offset Fixed Rate Home Loans funded by Bendigo Bank, the fixed rate is automatically locked using the applicable fixed rate on the date the application is approved. The Fixed Rate Lock is valid for 90 days and the customer must settle in no more than 90 days of the initial loan application for the locked-in fixed rate to apply. If the loan does not settle within 90 days, the applicable fixed rate for the loan type at the settlement date will apply. For Atlas Fixed Rate Home Loans, the fixed rate of the loan will be the applicable fixed rate at the time of settlement.
++ Offset facilities: Offset facilities are only available on the Qantas Money Offset Home Loan and Qantas Money Atlas Home Loan for both fixed and variable products. Offset facilities must be linked to an eligible Home Loan account and can only be linked to one eligible Home Loan account at any one time.
Up to 6 offset accounts are available per Qantas Money Offset Home Loan. Linked offset accounts must be in the same customer name/s as the loan account.
Up to 10 offset sub-accounts are available per Qantas Money Atlas Home Loan. Linked offset sub-account/s must be in the same customer name/s as the loan account. For Atlas Fixed Rate Home Loans, offset funds are limited to $20,000 per annum total across all sub-accounts. Additional funds may be subject to Early Repayment fees. Fees can be found on the fees page.
How to set up the offset facilities may change from time to time, and will be advised during the application process.
This is general advice only. Consider the relevant home loan Terms and Conditions and TMD, and your personal circumstances before you take out this product. Details can be found on the Terms and Forms page.
Complaints about the home loan or offset facilities should be made to the credit provider and provider of the offset facility by emailing: Basic and Offset Home Loans funded by Bendigo Bank: myloan@homeloans.qantasmoney.com Atlas Home Loans funded by ColCap Financial: colcap.myloan@homeloans.money.qantas.com
~ Service fees: A $15/month service fee applies to the Qantas Money Offset Home Loan. There is no ongoing monthly service fee for the Qantas Money Basic Home Loan. Other fees may apply.
± Classic Flight Rewards: Classic Flight Rewards are available on Qantas, Jetstar and partner airlines. Classic Flight Reward seats are subject to capacity controls, availability is limited and some flights may not have any Classic Flight Rewards available. Taxes, fees and carrier charges are payable by an Accepted Payment Card in addition to the points required. Qantas Points and taxes, fees and carrier charges quoted for Classic Flight Rewards are per person, for economy flights (unless otherwise stated) and accurate as at 10 October 2025 and are subject to change. These are quoted at the time of booking and are subject to change. Status Credits and Qantas Points will not be earned on Classic Flight Rewards. Visit Classic Flight Rewards for more information.
^^Atlas Annual Fee: For Atlas Home Loans, the term ‘annual fee’ may be referred to as ‘lender annual fee facility’ in some loan documents and contracts.